Q4 Most Active Quarter for the Industrial Market for Two Years
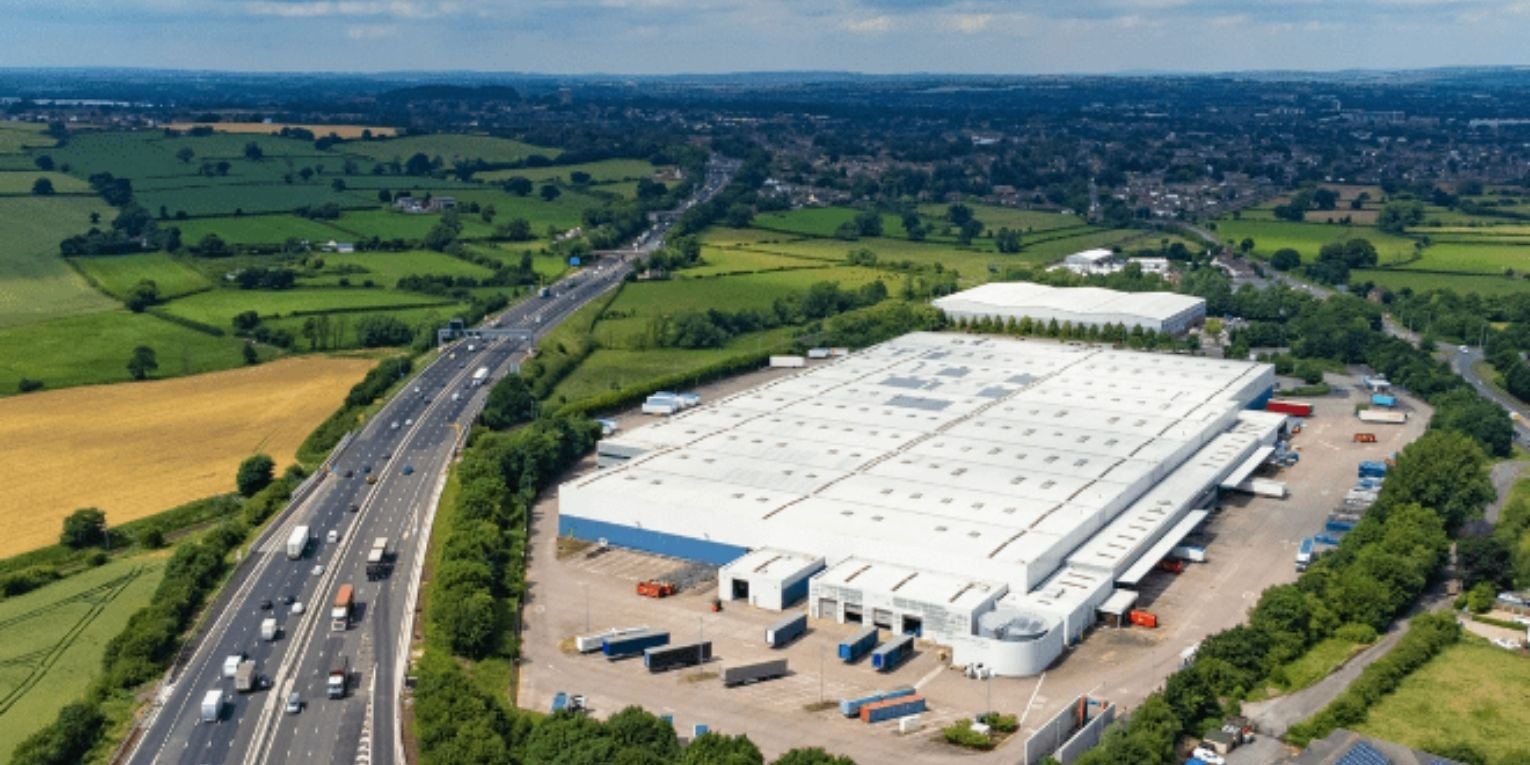
Colliers' Industrial and Logistics team reports that 8.8 million sq ft of warehouses of 100,000 sq ft or more were leased in the final quarter of 2024, the busiest quarter since Q3 2022. This took total big box take-up for the year to 28.2 million sq ft, up 18 per cent on 2023.
The Midlands accounted for around 60 per cent of take-up, reflecting its central location for occupiers reorganising their supply chains. Retailers and wholesalers, and third-party logistics and storage firms, each took 30 per cent of space, followed by manufacturers (22 per cent), other occupiers (nine per cent) and online-only retailers (six per cent), with three per cent unknown or confidential.
Colliers' latest Industrial Rents Map shows average UK prime rents for large distribution warehouses rose 5.4% year on year to £11.50 per sq ft, while mid-box and multi-let prime rents rose 4.3% to £15.15 per sq ft. Average land values were unchanged at £2 million per acre.
Len Rosso, Head of Industrial and Logistics, said recent years had been difficult because of global economic headwinds, but strong demand for prime space in core markets was keeping take-up in line with the long-term average and driving rental growth.
Speculative development of large warehouses fell from 20 million sq ft in 2023 to nine million sq ft in 2024, with a similar level expected in 2025. Available supply has risen five per cent on the quarter to 48 million sq ft, as secondary space returns to the market and four million sq ft of speculative space completes, putting vacancy at 8.0%.
Andrea Ferranti, Head of Industrial and Logistics Research, said high borrowing costs had held back speculative building and land values. While recent rate cuts may mark a turning point, expectations of higher inflation and weak growth are pushing bond yields up and slowing the recovery.