Fix and Flip Loans: A Comprehensive Guide for Beginners
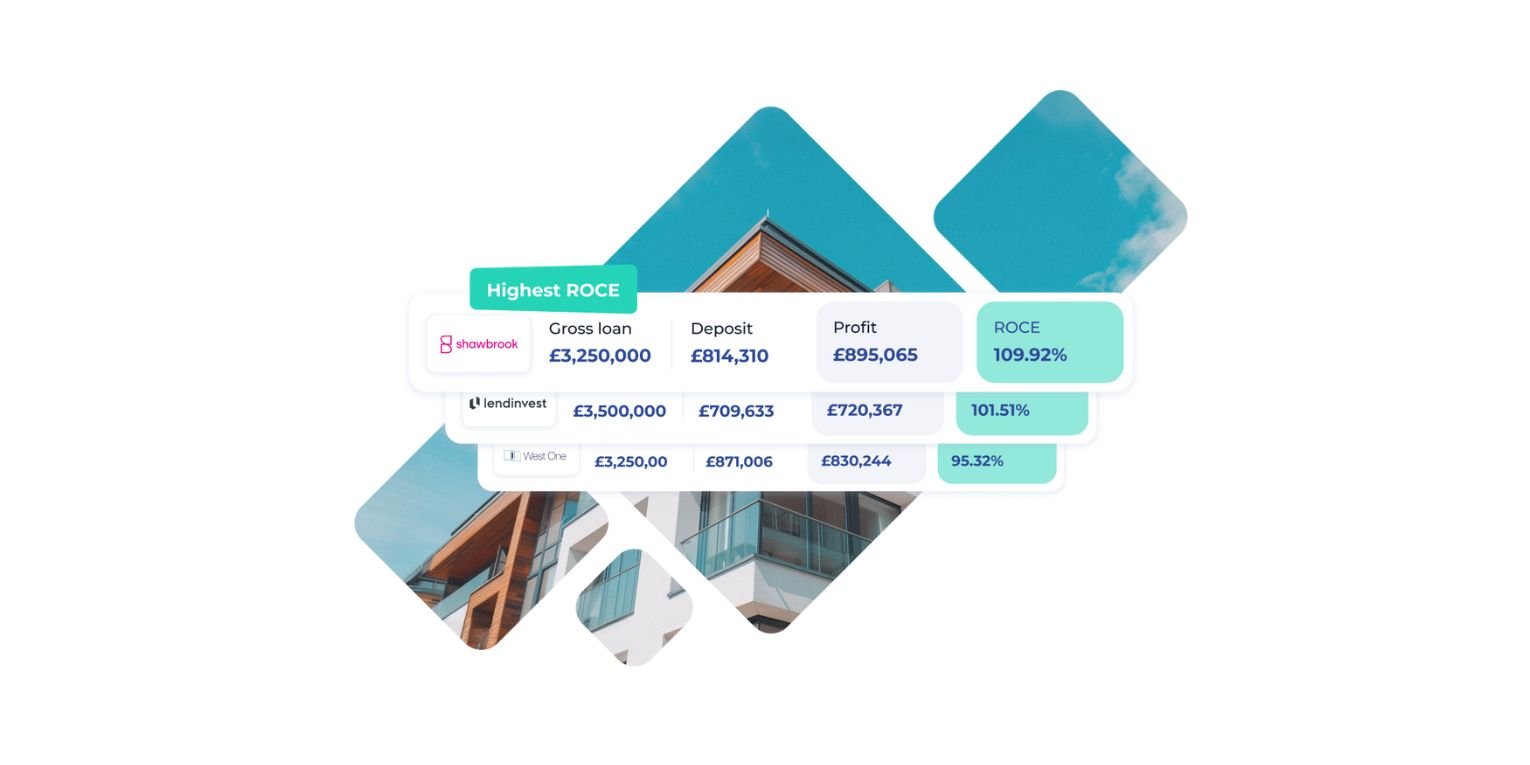
Brickflow's guide explains fix and flip loans, the finance used to buy a run-down property, renovate it and then sell or let it. The approach attracts both experienced and first-time investors, and the guide cites a study of 1,000 investors which found more than 60% of UK flips made profits of £10,000 to £75,000.
Fix and flip loans are a form of refurbishment bridging finance: short-term, quick to arrange, secured on property and repaid with interest at the end. Terms are typically 1 to 24 months (up to 60 with some lenders), loans range from £25,000 to £100 million, and lenders will usually advance up to 75% of the purchase price plus up to 100% of refurbishment costs. Completion typically takes one to six weeks, interest can be rolled up or serviced, and the exit is a sale or refinance.
Most flips are light projects of three to six months, such as new kitchens or bathrooms, layout changes, windows, heating, roofs and redecoration. Heavier work involving planning, conversions or extensions is possible, although development finance may suit better. On larger jobs, lenders often appoint a monitoring surveyor who releases funds in stages. Approval can take days for simple cases but around two weeks is more realistic, and regulated loans for a borrower's own home can take eight weeks or more.
Borrowers must generally be over 18 and UK resident, with a deposit to cover any shortfall, adequate security, a valuation and a clear exit plan. Good credit and experience help but are not essential.
Benefits include speed, flexibility, rolled-up interest, the ability to buy at auction or act as a cash buyer, and funding for refurbishment costs. Risks include higher costs than long-term lending, compounding interest, steep default rates if the term is overrun, and repossession on default.
The guide recommends thorough market research, several builder quotes, a contingency budget and checking finance costs before committing. To strengthen an application, investors should model the deal, prepare a detailed project pack, present a solid exit strategy and communicate openly with lenders. A specialist broker, a refinance agreement in principle or pre-sale contract, and a deposit of 40% or more can all help secure better terms.
Alternatives include development finance, other bridging products, commercial, residential, self-build and buy-to-let mortgages. The guide also mentions the rough "70% rule", under which investors pay no more than 70% of the finished value minus works, and notes that experienced flippers often aim for returns of at least 15%.